AI accelerates output, but accuracy is what protects client trust.
Accounting used to leave room to think, but now it runs at client speed, and it is still your signature that closes the month. Clients make decisions in real time, so their financial visibility has to keep pace. Tools promised more capacity, yet they handed you a part-time job in systems administration (permissions, sync gaps, mapping logic) plus the reconciliation work no one budgets for.
TLDR:
Here is the mistake the market keeps making.
The risk is not that AI is replacing accountants.
The risk is speed without accuracy.
The risk is automation without accountability.
It is liability with a dashboard.
Remove the accountant from the loop and the work does not disappear.
The judgment does.
That judgment is not overhead.
It is the job.
When execution gets cheaper, judgment becomes more valuable.
When validation is built in, capacity appears.
When books update in real time, advice follows in real time.
Automation works for tasks without consequences.
Accounting has consequences.
You cannot “mostly” tie out an account or “pretty much” comply.
That is why someone signs their name.
The data from 2026 makes the stakes concrete. Organization-wide AI adoption in professional services nearly doubled to 40% in a single year, according to Thomson Reuters. A separate 2026 survey by Uku of its own customer firms (a self-selected sample with no published sample size) found that 0% of respondents said they already fully trust AI to act on its own. That measures willingness to go fully autonomous, not confidence in the quality of AI output, which other surveys put well above zero (see the DataSnipper figures below). That is one self-selected survey about full autonomy, so it does not show how firms broadly feel about AI. It does point the same way as the larger surveys below: professionals are comfortable letting AI do the work, and most want a qualified person to approve the output. Firms that win aren't the ones with the most automation. They're the ones where the AI does the work and a qualified professional approves the output before it touches the books.
Vendors like Digits position autonomy as the core value, and autonomy lowers cost.
Firms absorb the cost when autonomy is wrong.
Puzzle is built on the opposite premise.
Let agents handle the repetition.
Let accountants lead with judgment.
The future is not fewer accountants.
It is accountants operating at a higher level.
Less manual work.
More judgment.
More advisory.
Accurate Books. At AI Speed.
Designed by accountants. Built on AI agents.
The data has caught up to the argument. Karbon's 2026 AI report found 98% of accounting professionals globally now report using AI. According to Thomson Reuters, organizational AI adoption in professional services jumped from 22% to 40% in a single year. And in the 2026 Intuit QuickBooks Accountant Technology Survey of 725 US accounting and bookkeeping professionals, 86% expect AI to increase their ability to deliver advisory work over the next 12 months, and only 6% want AI to execute client deliverables autonomously, the clearest signal that the profession is moving from compliance execution to guidance.
At the same time, the confidence gap is real. Survey after survey shows that speed is not the bottleneck. Trust is. Firms adopting AI are not betting on autonomy. They're building governed workflows where AI does the repeatable work and a qualified professional approves the output.

That is exactly what 2026 has made clear: the firms pulling ahead are not automating more. They're automating the right layer. Access to AI is nearly universal (98% of accounting professionals report using it), but DataSnipper found that only 13% of organizations have built AI into a defined workflow. Those firms have a repeatable path from agent output to accountant approval. The ones left behind are still running month-end close as a manual sprint instead of a continuously managed process.
The clearest structural shift underway is the move from point-in-time reporting to continuous close. Firms still treating the month-end as a single compressed event at the end of the period are absorbing all the error risk at once: every misfiled transaction, every account left without a bank match, every missed accrual surfaces in the same chaotic week. Firms that have adopted AI-assisted workflows are spreading that work across the month: transactions categorized daily, reconciliations running automatically, exceptions flagged early. By the time the calendar flips, most of the close is already done. That is not a workflow preference; it is a structural advantage that compounds as client load grows.
The math on firm growth has always been brutal: more clients means more bookkeepers, more bookkeepers means more overhead, more overhead means margins compress exactly when revenue is climbing. Most firms have accepted that equation as fixed.
It isn't.
The constraint was never the number of people. It was the volume of repetitive, rules-based work each person had to absorb before any real accounting could happen. Categorization. Reconciliation. Journal entry prep. Month-end close checklists. These tasks scale linearly with client count when done by hand. They don't have to.
When AI agents handle the repetitive execution layer (pulling transactions, mapping them to the right accounts, flagging anomalies, preparing the close), a single accountant can carry a noticeably larger client load without adding headcount. The accountant's time moves from data entry to review, from reconciliation to advisory, from month-end close to explaining what the numbers mean.
That shift changes the firm's unit economics entirely. Onboarding a new client no longer means hiring ahead of it. Capacity appears inside the existing team.

The firms that pull this off aren't automating everything. They're automating the right layer. Execution runs on agents. Approval stays with the accountant. That distinction matters: it's the approval step that keeps the work accurate and keeps the firm's liability where it belongs.
Puzzle is built for exactly this model. Agents handle the work. Accountants lead the outcome. Client books stay accurate at AI speed.
Newer survey data shows the trust gap widening as usage grows. DataSnipper's 2026 AI report on audit and finance professionals found that trust in AI to deliver quality at scale fell from 78% to 55% in one year. The drop was steepest among the people closest to the work: partners who review AI-assisted output trust it at 79%, while the individual contributors who produce it trust it at 50%.
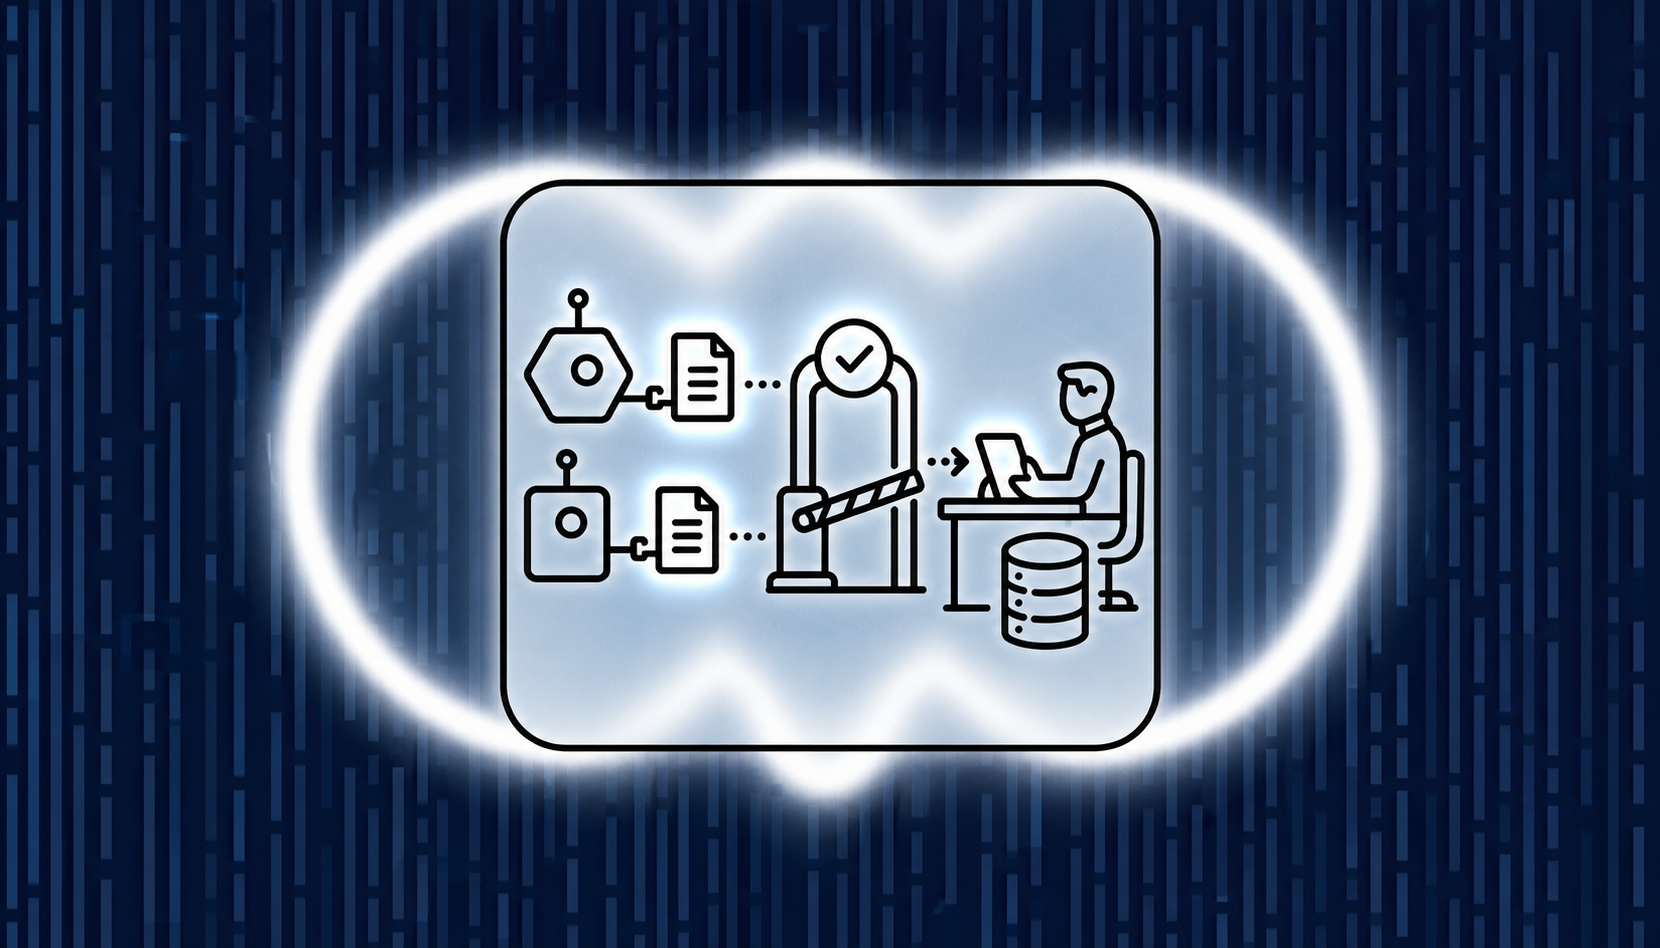
The same report shows where professionals draw the line. About 80% are comfortable letting AI extract data, compare documents and take a first pass. Only 38% are comfortable letting it make the final sign-off. Execution goes to the agent. Approval stays with the accountant.
Firm priorities are shifting in the same direction. In the AICPA's mid-year CPA Firm Top Issues Survey, published in June 2026 (629 respondents), change management for technology and AI ranked as the leading long-term issue. Because this is a mid-year snapshot, treat it as the position as of June, not a current reading. Technology and AI ranked in the top two for five of six firm-size groups. Two years earlier, technology issues appeared only in the smallest and largest groups and ranked fourth or fifth.
The gap between access and adoption is where firms get hurt. DataSnipper found that only 13% of organizations have built AI into a defined workflow, and only 56% have clear ownership of AI governance. If you are adding agents to your client work this quarter, name who reviews what first. Let agents draft categorization, journal entries and close prep, and have an accountant approve before anything posts.
The profession's standard-setters are now saying the same thing in print. In a November 2026 Journal of Accountancy feature, AICPA chief auditor Jennifer Burns, CPA, said AI “is changing the way we do our work, but it's not changing our professional requirements with respect to professional skepticism, use of judgment, appropriate supervision, and review.” AICPA ethics vice president Carl Mayes put the goal plainly: a human in the lead, with clear responsibility for the engagement, which goes beyond keeping a human in the loop.
The AICPA's October practice aid, Artificial Intelligence (AI) Considerations for Financial Statement Auditors, is written for auditors, but the logic carries over to bookkeeping and close work. Mayes's test: treat an AI tool like a very bright first-year associate who still needs diligent supervision and review. The same Journal of Accountancy article cites a 2026 IDC survey of about 1,000 audit and assurance professionals in six countries, where 64% said auditors should always validate the AI results they rely on.
If you are adding agents to client work this quarter, the governance checklist is short: a named reviewer for each workflow, access controls, an audit trail, and change management for any tool that touches client books. That is the model Puzzle follows. Agents draft the categorization, journal entries and close prep, an accountant approves before anything is final, and the audit log records who created or modified each transaction.
Accurate enough to handle most of the work, but not accurate enough to remove the human entirely. By Puzzle's own measure, its AI categorizes about 90% of transactions automatically and finalizes about 85%. Daily bank reconciliation runs natively with Mercury and Ramp (other banks need manual CSV uploads), and Puzzle maintains both cash and accrual books, updated daily. For a 10-person startup, that means the books stay current without a bookkeeper logging in every day. But "accurate enough to replace" is the wrong frame. The right question is: what does the human actually need to do?
At that stage, the answer is review and judgment, not execution. AI handles the repetitive layer (categorization, reconciliation, journal entry prep), and a qualified reviewer (an accountant, a Puzzle partner, or a founder with accounting fluency) approves the output before the close. That approval step is what keeps the books defensible when a VC requests financials or a CPA prepares taxes. In Uku's 2026 customer survey, 0% of responding firms said they fully trust AI to act without a human checking first. This reflects liability, not technology limits: someone still signs their name, even though AI does the heavy lifting.
For a 10-person startup: you do not need a full-time bookkeeper when AI handles execution. You need a qualified reviewer at the close, whether that is a fractional accountant, a Puzzle delivery partner, or a founder who reviews the AI's output monthly. The cost of that review is far lower than a full-time hire, and the books are more accurate because the AI catches issues a tired human misses.
For a pre-seed or seed-stage startup without a full-time accountant, the right tool is one that keeps books accurate automatically, without requiring someone on staff to manage it daily. Puzzle is built for this: AI agents categorize transactions, match accounts to bank records, and maintain both cash and accrual books in real time, so founders have current financial visibility without a bookkeeper logging in every day. Tools like QuickBooks Online, Xero, and Ramp each handle parts of this, but they weren't architected around AI-native automation. They were built for manual workflows that AI features were later bolted onto. At the one to 15 person stage, accounting agent software for startups should deliver accuracy without overhead: books that update automatically, a close that doesn't require a three-day sprint, and numbers a founder can trust when a VC asks for them.
Many accounting tools that advertise AI use it for categorization suggestions or anomaly flagging, not for end-to-end execution of the month-end close. Puzzle is designed differently: AI agents run the close workflow, including journal entry preparation and account reconciliation, and surface the output for accountant review before anything is finalized. The agents do the work; the accountant approves the result. That distinction (AI bookkeeping automation vs. judgment) is what makes the close both fast and defensible. Removing the review step introduces risk and moves liability onto the firm without the control to manage it.
| Capability | Most tools | Puzzle |
|---|---|---|
| Transaction categorization | Suggestions only (human confirms each) | Automated, rules-based with learned patterns |
| Anomaly flagging | Yes | Yes |
| Journal entry preparation | Manual or semi-manual | AI agents prepare; accountant approves |
| Month-end close execution | Checklist-driven by a person | Agents run the workflow on a schedule |
| Accountant review step | Varies, often optional | Built in before anything touches the books |
| Fully autonomous close (no human) | Some tools offer this | Not supported: an accountant approves every close |
The most effective approach is to separate the execution layer from the judgment layer. Execution (pulling transactions, applying categorization rules, matching accounts to bank records, preparing accrual entries) is rules-based and repeatable. It should run on agentic AI for month-end close, not on a person working through a checklist. Judgment (reviewing the output, catching edge cases, approving the close, advising the client) is irreplaceable and is where the accountant's time belongs. In practice: set up automated transaction sync across the client's fintech stack (Stripe, Mercury, Ramp, Brex, Gusto), configure categorization rules at onboarding, let agents run the close prep, and build a short accountant review step before sign-off. For startups, the automated month-end close should produce daily-updated burn and runway figures, not a monthly snapshot delivered two weeks late.
Puzzle connects natively to Stripe and handles all three Stripe transaction types automatically: gross revenue is recognized, processor fees are split out as a separate expense line, and net payouts match the bank deposit. Most accounting software handles these types (gross revenue events, processor fees, and net payouts) poorly, because a manual or rule-based system requires separate rules for each, and those rules break every time Stripe changes a payout structure or fee format. Categorization starts with higher baseline accuracy because the system was built around startup transaction patterns, not adapted from generic accounting templates; Puzzle's AI categorizes about 90% of transactions automatically and finalizes about 85%. The practical result: Stripe income and expenses land in the right accounts without anyone touching them, and the reconciliation between Stripe and the bank account closes cleanly each month.
Bookkeeper categorization errors are almost always a systems problem, not a people problem. Manual categorization requires a human to recognize every vendor, match it to the right account, and apply consistent judgment across hundreds of transactions every month. One unfamiliar vendor name, one distracted afternoon, or one change in how a payment processor formats a payout, and the category is wrong. Those errors compound: a misclassified expense in January shows up in your P&L all year.
AI-native categorization removes the recognition problem entirely. Puzzle learns your specific vendors and transaction patterns, applies categorization rules automatically, and flags only the transactions where confidence is low. When your bookkeeper (or you) corrects a category, the system updates its rules for similar transactions going forward. The longer you use it, the fewer corrections are needed, because the model is learning your chart of accounts, not applying generic accounting templates.
The result is not that the bookkeeper disappears. It is that the bookkeeper stops doing the work that generates errors in the first place. Review and judgment stay with the human. Pattern-matching across hundreds of routine transactions goes to the AI.
CoWork is the agent layer in Puzzle's AI suite. It runs repeatable accounting workflows on a schedule instead of waiting for a human to trigger them: pulling and syncing transactions across connected accounts, applying categorization rules, preparing journal entries, and flagging anomalies for review. It can handle revenue recognition logic for SaaS and subscription businesses, map transactions to the right accounts based on learned patterns, and generate month-end close prep outputs that an accountant reviews before sign-off. For a fuller picture of what accounting agents do to your books, the distinction that matters is this: CoWork executes, but it does not approve. Every material output surfaces to the accountant before it touches the books. That keeps the workflow fast without removing the judgment step that makes the books defensible.
QuickBooks' automated categorization depends on manually configured rules, which means a human still has to touch many transactions. Puzzle's AI categorizes about 90% of transactions automatically and finalizes about 85%, learning from your specific chart of accounts, your vendor history, and the corrections you make over time. When confidence is low, it assigns no category instead of guessing, so flagged items are ones that genuinely need attention, not noise from bad auto-fills.
The improvement mechanism is direct: when you finalize a transaction or correct a category, the system creates a rule for similar transactions going forward. A new account will see lower accuracy until enough history and rules are in place, which is expected and worth setting as an expectation during onboarding. A mature account with a year of history will need far fewer manual corrections than a fresh one.
The practical difference versus a rule-based system: QuickBooks rules are static and break every time a vendor name changes or a new transaction type appears. Puzzle's model adapts. You spend less time fixing misfires over time, not more.
Puzzle's categorization model improves as it processes more transactions in your specific chart of accounts. When you correct a category or approve a suggestion, the system updates its pattern matching for similar transactions going forward, so the longer you use it, the fewer manual corrections are needed. For founders without an accounting background, Puzzle includes an AI chat interface: you can ask questions like "what was our largest expense category last month" or "show me all transactions over $5,000 that haven't been categorized" and get direct answers without reading a ledger. The intent is that a non-accountant can maintain visibility and catch obvious issues, while an accountant reviews and approves before the close. You don't need to understand debits and credits to use the day-to-day interface, but you do want a qualified reviewer before anything goes to investors or the IRS.
Migration from a tool like Wave, QuickBooks, or Xero into Puzzle starts with exporting your chart of accounts and historical transaction data. Then you map existing account categories to Puzzle's structure. Puzzle's onboarding process is designed to respect the categorization you've already done: transactions imported with existing categories are treated as reviewed, so you're not re-doing work that's already correct. The more important question is the cutover date. Most firms migrate at the start of a new fiscal year or quarter to keep historical comparisons clean. If your historical books have known errors or inconsistencies, the migration is also an opportunity to correct them before they carry forward. Puzzle's team works through this with new firms instead of leaving it as a self-serve import.
Puzzle's QuickBooks Connect button imports your historical financial data directly, so nothing has to be retyped. Connect is a one-time import of history, not a live sync, so plan to run the books in Puzzle after cutover. For QuickBooks Online, the direct integration takes a couple of days. QuickBooks Desktop, Xero and Zoho Books go through a manual process of about five to seven days. Migration costs $149 per system moved, charged once per system. If you are weighing the move, the QuickBooks alternative for startups page covers what changes day to day.
Two steps protect your history. First, export your own backup from QuickBooks before you cut over (reports, chart of accounts, attachments) so you always have a copy outside any system. Second, if your historical books are messy, import a cleaned trial balance as the opening balance or pick a clean go-live date, instead of carrying years of raw transactions forward. Flag disorganized QuickBooks data early so the cutover plan accounts for it.
Puzzle runs month-end close for startups as a continuously managed workflow instead of a sprint at the end of the month. Throughout the month, AI agents pull transactions from connected accounts (Stripe, Mercury, Ramp, Brex, Gusto), apply categorization rules, match accounts against bank feeds, and flag exceptions for review. By the time you reach close, most of the work is already done.
The close itself follows a checklist: review flagged transactions, confirm any accrual entries (deferred revenue, prepaid expenses, depreciation), approve the reconciliation output, and sign off. On Core plan and above, Puzzle's automated close checklist tracks each step. Nothing posts until an accountant or qualified reviewer approves it.
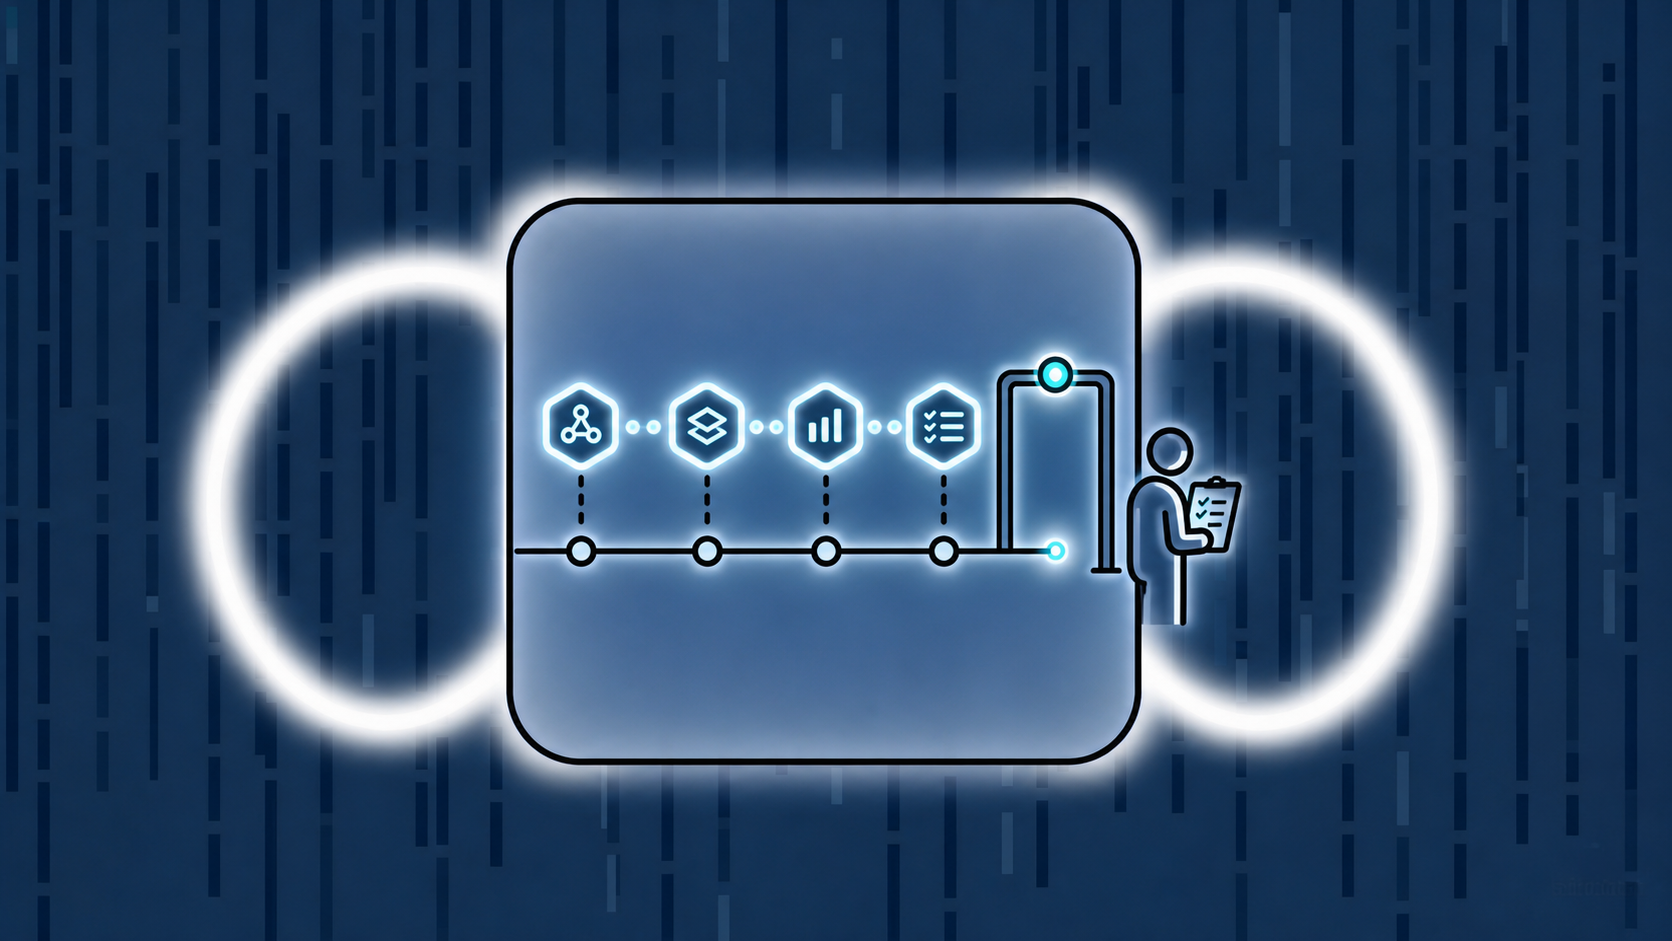
On the trust question: your books are ready to share when every transaction is categorized and finalized, accounts match your bank and card statements, and a qualified reviewer has approved the output. For investor diligence or tax filing, that reviewer should be a CPA or a Puzzle delivery partner, and the AI output alone is not enough. The AI handles execution; a human signs off. That sign-off is what makes the books defensible, and as noted above, the same principle holds across the profession.
Dual-basis accounting keeps two sets of books from the same transactions: cash basis records revenue and expenses when money moves, and accrual basis records them when they are earned or incurred. Puzzle maintains both simultaneously, so there is no second ledger to build and no manual toggle to keep in sync. The cash and accrual books update daily from the same data.
Here is how the two views differ. Say a customer pays $12,000 upfront in January for an annual SaaS contract. On a cash basis, you record $12,000 in January. On an accrual basis, you recognize $1,000 each month and carry the rest as deferred revenue. Founders watch the cash view for burn and runway, while investors and GAAP-style statements expect accrual.
Puzzle automates the accrual side for revenue recognition, deferred revenue, depreciation and amortization, and you can set custom accrual dates on individual transactions. Two limits to know: revenue recognition is Stripe-centric, so non-Stripe billing needs manual journal entries, and depreciation is straight-line only (MACRS and tax depreciation methods need manual journal entries). When you compare tools, check whether they keep both books at once or only switch a report between cash and accrual views.
Puzzle's multi-entity portal puts several companies under one login at no additional charge, so a founder or bookkeeping firm managing multiple clients can switch between entities without separate subscriptions or an ERP rollout. For locations and segments, classes let you filter P&L by location or business line (Complete plan and above), and Puzzle also tracks project-level and customer-level P&L. It is sized for startups and small teams that have outgrown a single set of books but are not ready for an ERP.
One limit to plan around: each entity keeps its own books, and Puzzle does not run native consolidations or eliminations across parent and subsidiary entities. Teams that need a consolidated view use Puzzle's integration partner Join. Puzzle also supports USD and US entities only, so multi-currency or international structures are out of scope.
For the daily work, yes. Puzzle's AI-native engine categorizes about 90% of transactions automatically and finalizes about 85%, and it runs accuracy reviews in the background without prompts. Daily reconciliation is native for Mercury and Ramp; other banks need manual CSV uploads. When the AI's confidence falls below 99%, it assigns no category and flags the transaction for review instead of guessing.
The close still needs a human sign-off, which is by design. Founders typically spend about 15 to 20 minutes per week finalizing AI-categorized transactions, and the Request Reviewer feature lets a designated person approve and categorize by email reply without logging in. For the month-end itself, AI Close gives an accountant a structured, AI-assisted close with review and approval at every step. Nothing changes in the books without user approval, so you skip the daily login but keep the accountability.
The right time to start is the day you open a business bank account or take your first dollar of investment, not when you're about to file taxes or raise a round. Early books are cheap to maintain and expensive to reconstruct. The common mistake is waiting until there are 18 months of uncategorized transactions to clean up before a Series A diligence process. On the CPA question: you don't need a CPA to maintain day-to-day books, but you do need one (or a qualified accountant) at specific moments (entity formation, your first 83(b) election, tax filing, and any fundraising round where investors will review financials). For the period between those milestones, accounting software that runs automatically keeps the books clean without requiring accounting expertise. When the CPA does come in, they're reviewing accurate, current records, not reconstructing 18 months of transactions on a deadline.