The month end close process doesn't have to take days or feel like a mystery. But if no one's ever walked you through what it actually involves, it's easy to either skip it or do it wrong, and not find out until fundraising due diligence. Here's what it looks like when you're a first-time founder doing it with a lean setup.
TLDR:
The month-end close is the process of locking down your financial records at the end of each calendar month. Every transaction gets reviewed, categorized, and confirmed so your income statement, balance sheet, and other reports reflect exactly what happened during that period.
Ongoing bookkeeping records transactions as they come in. The close is the checkpoint where you verify everything is accurate, complete, and consistent before the month is sealed. For a startup, that means confirming your revenue, expenses, and bank balances all agree, nothing is missing, and your financial statements are reliable enough to act on.
Skipping the close feels harmless when things are going well. It stops feeling harmless the month you calculate your burn rate and realize your runway is two months shorter than you thought.
The close produces the financial snapshot your whole operation runs on. Burn rate, runway, and cash position: none of those numbers are reliable if the underlying close is sloppy. If the inputs are wrong, the decision is wrong.
Surveys suggest founders spend 8-12 hours a month on bookkeeping for relatively simple transaction flows. The problem is when founders skip it and only find discrepancies during fundraising due diligence, or after making a call they can't reverse.
A clean, timely close gives you the window to course-correct. A delayed one takes that window away.
According to APQC's benchmarking data across 10,198 organizations, the median close takes 6.0 calendar days, yet 50% of finance teams still take over a week. For early-stage startups with simpler structures, the target should be shorter. Manual processes are usually why it isn't, which is where financial close automation software comes in.
The process follows a logical sequence once you know what you're looking for.
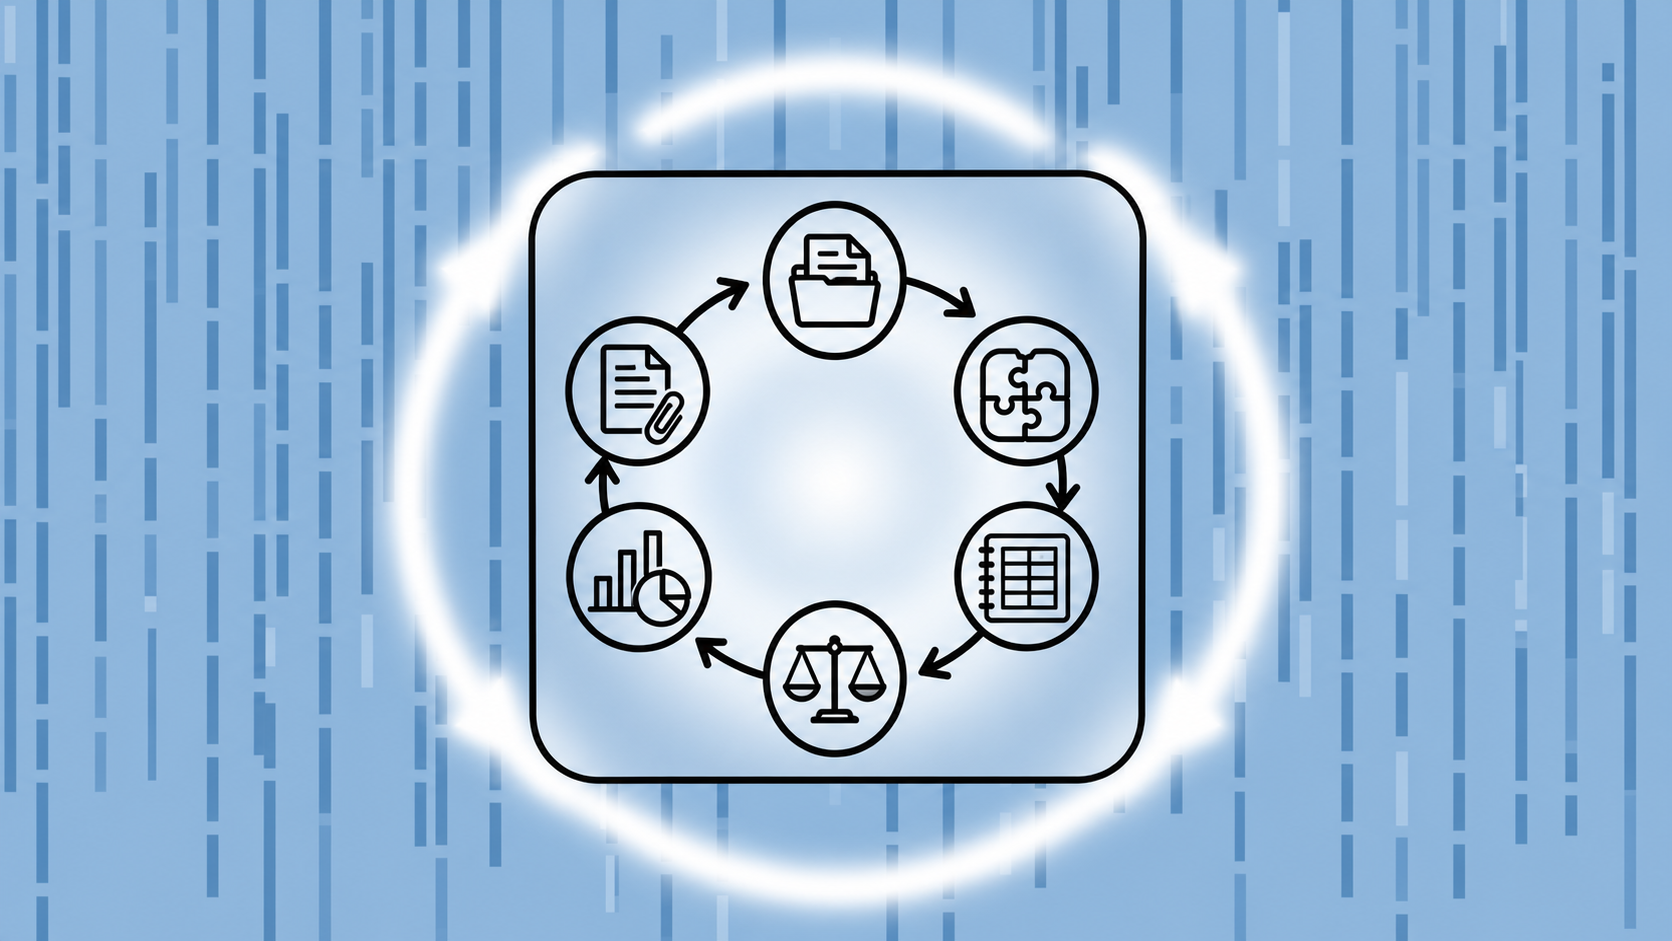
Each step feeds the next. Skipping reconciliation means your adjusting entries are built on shaky data, and your statements inherit those errors downstream.
At early-stage startups, the answer is usually the founder, at least at first. There is no controller, no CFO, and often no full-time bookkeeper. The close either happens because the founder made it happen, or it quietly doesn't happen at all.
The realistic division of labor looks something like this:
Where it gets tricky is the middle stage: past the point where a founder can manage it alone in an hour, but not yet at the scale that warrants a full-time finance hire. The goal is matching the labor to your actual complexity, not over-buying before you need it.
Most close delays trace back to the same handful of problems.
Disconnected systems are the biggest one. If your bank, payroll tool, and billing software don't talk to each other, someone has to manually pull and cross-check data across all of them, which is exactly what automated bank reconciliations are meant to fix. That manual handoff is where errors hide and hours disappear.
Manual transaction categorization compounds this. When every transaction needs a human to touch it, categories get rushed or guessed, and you end up with adjusting entries later to fix what should have been right the first time.
Late-arriving information is harder to control but just as damaging. A vendor invoice that shows up on the 8th, a reimbursement submitted after the period ends, an accrual your accountant forgot to flag: each one forces you to either reopen the close or carry an error forward.
Without a clear checklist of what still needs to happen, the close has no finish line. Founders end up asking "are we done?" and getting "I think so" as an answer.
| Phase | Timing | Tasks |
|---|---|---|
| Pre-close | Last 3-5 days of month | Confirm all invoices are sent; chase outstanding vendor bills; flag any unresolved transactions in your accounting software |
| Execution | Days 1-3 after month-end | Balance all bank and credit card accounts; finalize transaction categories; post payroll entries; record accruals and prepaid amortization |
| Execution | Days 3-5 after month-end | Post depreciation entries; confirm revenue recognition is current; review balance sheet for anything that looks off |
| Post-close | Days 5-7 | Run income statement and balance sheet; compare to prior month; lock the period |
Three things trip up first-time founders more than anything else:
The pre-close window is where most founders lose time. Walking into day one with unresolved transactions means you're reconstructing the month instead of reviewing it.
Four practices make the biggest difference at startup scale.
Start pre-close work before the month ends. Walking into day one with a clean transaction queue and all invoices sent cuts reconstruction time in half. The close should be a review, not a rescue operation.
Write the process down. A checklist that lives in someone's head disappears the moment that person is sick, traveling, or stretched thin. Document who owns each step and when it's due.
Assign clear ownership. If everyone is responsible for reconciliation, no one is. Each task needs a name next to it.
Automate reconciliation and categorization wherever possible using close automation tools built for startups. According to benchmarking data from Debit & Co., only 31% of organizations automate most or all of their reconciliations. Among those that do, Ventana Research data cited in that report shows 54% finish their quarterly close within six business days, compared to just 21% with minimal automation. Manual reconciliation is where time goes to die, and where errors compound before anyone catches them, which is why more teams are turning to accounting automation software for startups.
Human review still matters at the end. Automation handles volume; judgment handles edge cases. Spend your time on the second, not the first.
Investors reviewing your financials can tell quickly whether your books were maintained month by month or reconstructed in a panic before the data room opened. Gaps in the close record, unexplained adjusting entries, or revenue figures that shift between versions are all flags that signal fragile financial controls.
What investors actually want to see:
If you're targeting a seed or Series A in the next 12 months, getting your startup finances in order means your close process needs to be repeatable now. Cleaning up 18 months of sloppy books under diligence pressure is expensive and signals exactly the operating risk investors price into their terms.
Transaction categorization runs at up to 98% automation, so the manual review that used to consume a full evening shrinks to roughly 15-20 minutes a week. Bank reconciliation that formerly took two hours now takes five minutes, up to 96% faster.
Customers who fully onboard and connect supported integrations are eligible for a subscription refund if they don't see at least a 50% reduction in month-end close time within 60 days.
The automated close checklist (Core plan and above) gives the close a real finish line. Because the checklist keeps you on top of transactions throughout the month, you're reviewing the close, not reconstructing it. For founders who want human oversight alongside the software as they automate month-end close, vetted Puzzle partner firms handle review and finalization. Puzzle never competes with those accountants for the client relationship.
Your close process is only as good as how consistently you run it. Sloppy months compound into messy books, and messy books show up at the worst possible time, usually right before a funding conversation. The goal is a close that takes days, not weeks, with numbers you trust. Book a demo to see how founders use Puzzle to get there.
For an early-stage startup, a well-run month-end close process should take three to five business days after period-end. The APQC benchmark across 10,198 organizations puts the median at 6.0 calendar days, but simpler startup structures should beat that. Manual processes are usually why they don't.
Connect your accounts directly to accounting software that pulls transaction data in real time. Puzzle integrates natively with Mercury, Ramp, Stripe, Brex, and others, updating your cash position, burn rate, and runway daily so you're watching the numbers all month instead of reconstructing them after the period closes.
QuickBooks retrofits AI onto legacy architecture and achieves 20 to 40% automated categorization accuracy. Puzzle was built AI-native from the ground up and categorizes up to 98% of transactions automatically, cutting bank reconciliation from two hours to five minutes. For founders running a close themselves, that difference is the gap between a full evening and a 15 to 20 minute weekly review.
Start pre-close work in the last three to five days of the month: confirm all invoices are sent and flag unresolved transactions before the period ends. Then balance your accounts first, post adjusting entries second, and lock the period before moving on. Automation handles categorization and reconciliation volume; your time goes to the final review, not the reconstruction.
Yes, with the right setup. Investors want monthly financials that close within a week of period-end, clean income statement and balance sheet reconciliation, and correct revenue recognition for any deferred components. Accounting software with automated categorization, dual-basis accounting, and a structured close checklist can produce those statements consistently. And if you want a human review layer, vetted bookkeeping partners can handle adjusting entries and sign-off without requiring a full-time hire.