The collapse of Silicon Valley Bank and now First Republic Bank was an unfortunate wake-up call to how important it is for founders to know their cash positions and cash risks at all times. Managing cash is more complicated and risky than many of us realized. At Puzzle, we get that, and we want every founder to have confidence in understanding all their cash, from everywhere, all at once.
A broadly observed response among startups to the SVB collapse has been spreading funds across multiple institutions to ensure FDIC coverage in case of future collapses.
TLDR:
One common misconception is that there is $250k coverage for each bank account. We’ve read the fine print and are here to tell you that’s not true. FDIC coverage is limited to $250k per depositor per category per institution. Say you have a checking account, savings account, and money market deposit account. These accounts would be pooled together in one category and insured up to $250K in aggregate.
We recommend all startups review the FDIC’s excellent FAQ about how FDIC insurance works.
The main benefit of spreading your cash between banks is protecting your cash against risk, but doing so also makes it harder to track all your cash, in a single view, in real-time. Puzzle now makes it easy to see your total cash and total FDIC coverage in a single snapshot across different banks.
Three years after SVB collapsed, the $250K FDIC coverage limit is still $250K — and the reform debate is still ongoing. In December 2025, the FDIC finalized a special assessment rule to recoup losses from the SVB and Signature Bank failures, a direct consequence of the systemic risk exception invoked in 2023. Meanwhile, the FDIC has been actively “rightsizing” its regulatory posture: streamlining examinations, easing bank-fintech partnership rules, and opening the door to digital asset activity for insured institutions.
What this means for startups: the structural risk that spooked founders in 2023 hasn't been eliminated by new law. Congress has not raised the standard deposit insurance cap, and the FDIC itself has signaled that any further increases would require legislative action. The multi-bank sweep strategies covered below remain the most practical way to protect cash beyond $250K — and the case for monitoring your coverage in real-time is just as strong now as it was when SVB went down.
If you’re not interested in holding your cash in 50 different bank accounts (like Giannis Antetokounmpo), don’t worry. To enhance your coverage at a single bank, you can follow some strategic methods. Here are two options you should consider:
Mercury Vault | Brex Business Account | |
|---|---|---|
| Max FDIC coverage | Up to $5M | Up to $6M |
| Partner banks | Up to 20 | Up to 24 |
| Account type | Bank account (via Choice Financial Group & Column N.A.) | Cash management account |
| Additional options | Sweep network | Government money market mutual fund |
Maximum Coverage: Up to $5M
Mercury is a financial technology company that works with over 300,000 businesses, including venture-backed and bootstrapped startups. Mercury Vault is a risk-management solution that provides suggestions on how startups can allocate their cash to mitigate risks and protect their funds. Through its partner FDIC-insured banks (Choice Financial Group and Column N.A.) and sweep networks, your deposits are spread across up to 20 different banks that are managed through one single account in Mercury. If you're evaluating accounting software for Mercury users, this solution can provide up to $5 million in FDIC insurance.
Maximum Coverage: Up to $6M
Brex offers a suite of financial products to over 35,000 companies. In addition to offering spend management tools and credit cards, Brex also offers banking solutions, like the Brex business account. The Brex business account is a cash management account (not a bank account) that operates like a business bank account. It allows you to store deposits across up to 24 partner banks or in a government money market mutual, which can make you eligible for FDIC insurance of up to $6 million in total. For a deeper look at how Brex fits into a startup's financial stack, see our guide to Brex for startups.
How can you continue to ensure your ongoing protection keeps pace as you grow?Puzzle has built two free tools for monitoring your FDIC coverage:
The FDIC Coverage Monitor is a quick way for Puzzle users to access and view their estimated FDIC coverage at any time.
Say goodbye to manually keeping track of all your bank balances and coverage in a spreadsheet. In Puzzle, depository balances less than $250k at a bank are tagged as “Covered,” while depository balances greater than $250k are tagged “At risk.”
Investment accounts — such as Treasury and Brokerage accounts — are tagged “Not eligible” for FDIC coverage.
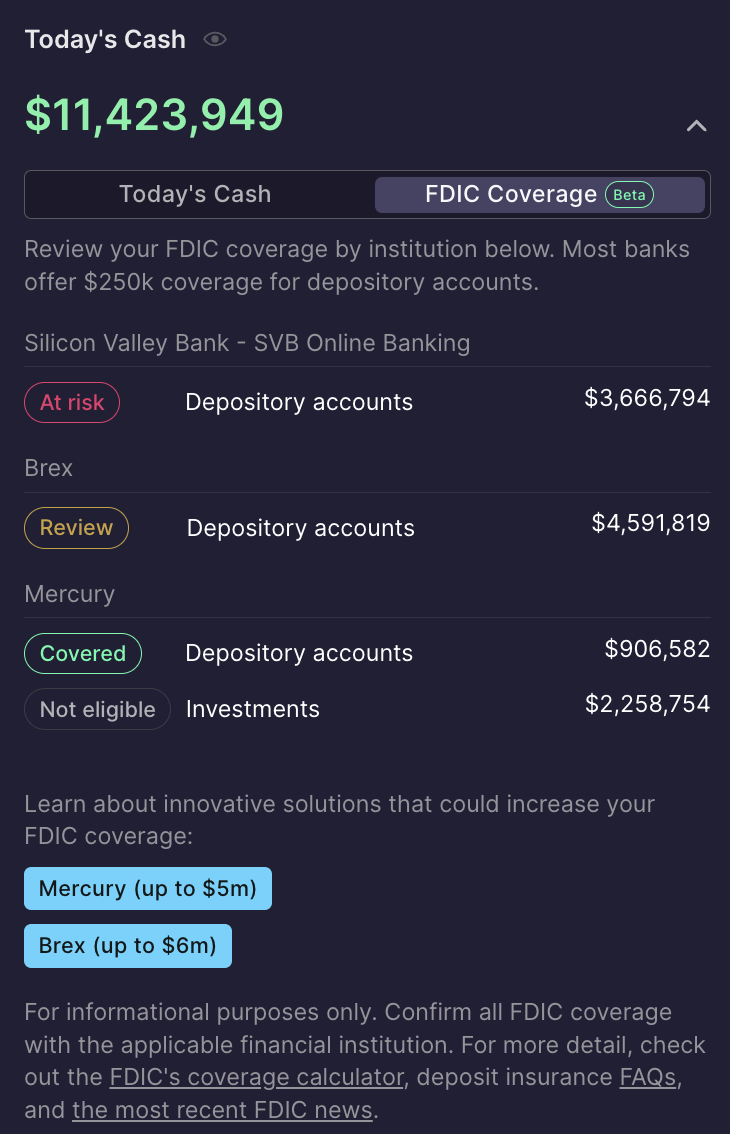
While many accounts not offering FDIC coverage are still great options offering high yield without extreme risk, we want you to make informed decisions based on your current coverage and risk tolerance. And we are equipped to do this for you!
*Puzzle’s estimate is for informational purposes only. Confirm all FDIC coverage with the applicable financial institution and the FDIC website.
While Puzzle is able to estimate your FDIC coverage based on its $250k coverage for depository accounts at each bank, FDIC offers its own FDIC coverage calculator that enables you to review FDIC coverage for each bank you use. You can also review the depository insurance FAQs on the FDIC website to make sure you are making an informed decision about moving your money between accounts.
Mercury provides users with a view of current FDIC coverage. To see which banks your money is allocated to, you can select “Docs & Statements” and download your Sweep statement.
Within a Brex account, you can choose a custom allocation between FDIC-insured cash and money market funds (not FDIC-insured) within Settings → Company → Allocation → Manage. This method allows you to allocate current funds and set up rules for where to allocate future funds.
Puzzle pulls balances and transactions directly from your connected bank and fintech accounts in real time. If a transaction hasn't synced yet — because of a bank delay or a manual account that can't be connected — that balance won't appear in your Today's Cash View or FDIC Coverage Monitor until it does. For accounts that can't be linked automatically, you can add them manually so the snapshot stays complete. Puzzle flags the last-synced timestamp for each account so you always know whether you're looking at live data or a slightly stale balance.
Yes. Puzzle connects to your Mercury and Brex accounts the same way it connects to any other bank account. The FDIC Coverage Monitor uses the reported balance at each institution to estimate your coverage — so if your sweep product spreads funds across multiple partner banks, the monitor reflects the balances Puzzle can see. For the most precise picture, confirm your exact allocation directly with Mercury or Brex, since the underlying sweep distribution may update daily.
The FDIC Coverage Monitor is a free tool available to all Puzzle users. You don't need a paid plan to see your Today's Cash View or your estimated coverage breakdown — just connect your bank and fintech accounts and the snapshot updates automatically.
As your financial situation shifts and you allocate assets between multiple bank accounts, having a single view of your cash is important. A single snapshot allows you to:
Puzzle simplifies the process of gaining cash insights that help you make better business decisions. Pulling together a real-time cash analysis — including FDIC coverage — can be a time-consuming, tedious, and challenging task. Make your finance and accounting automated, easy, and intuitive.
For more information about FDIC coverage, refer to the FDIC coverage calculator, depository insurance FAQs, and the most recent FDIC news.